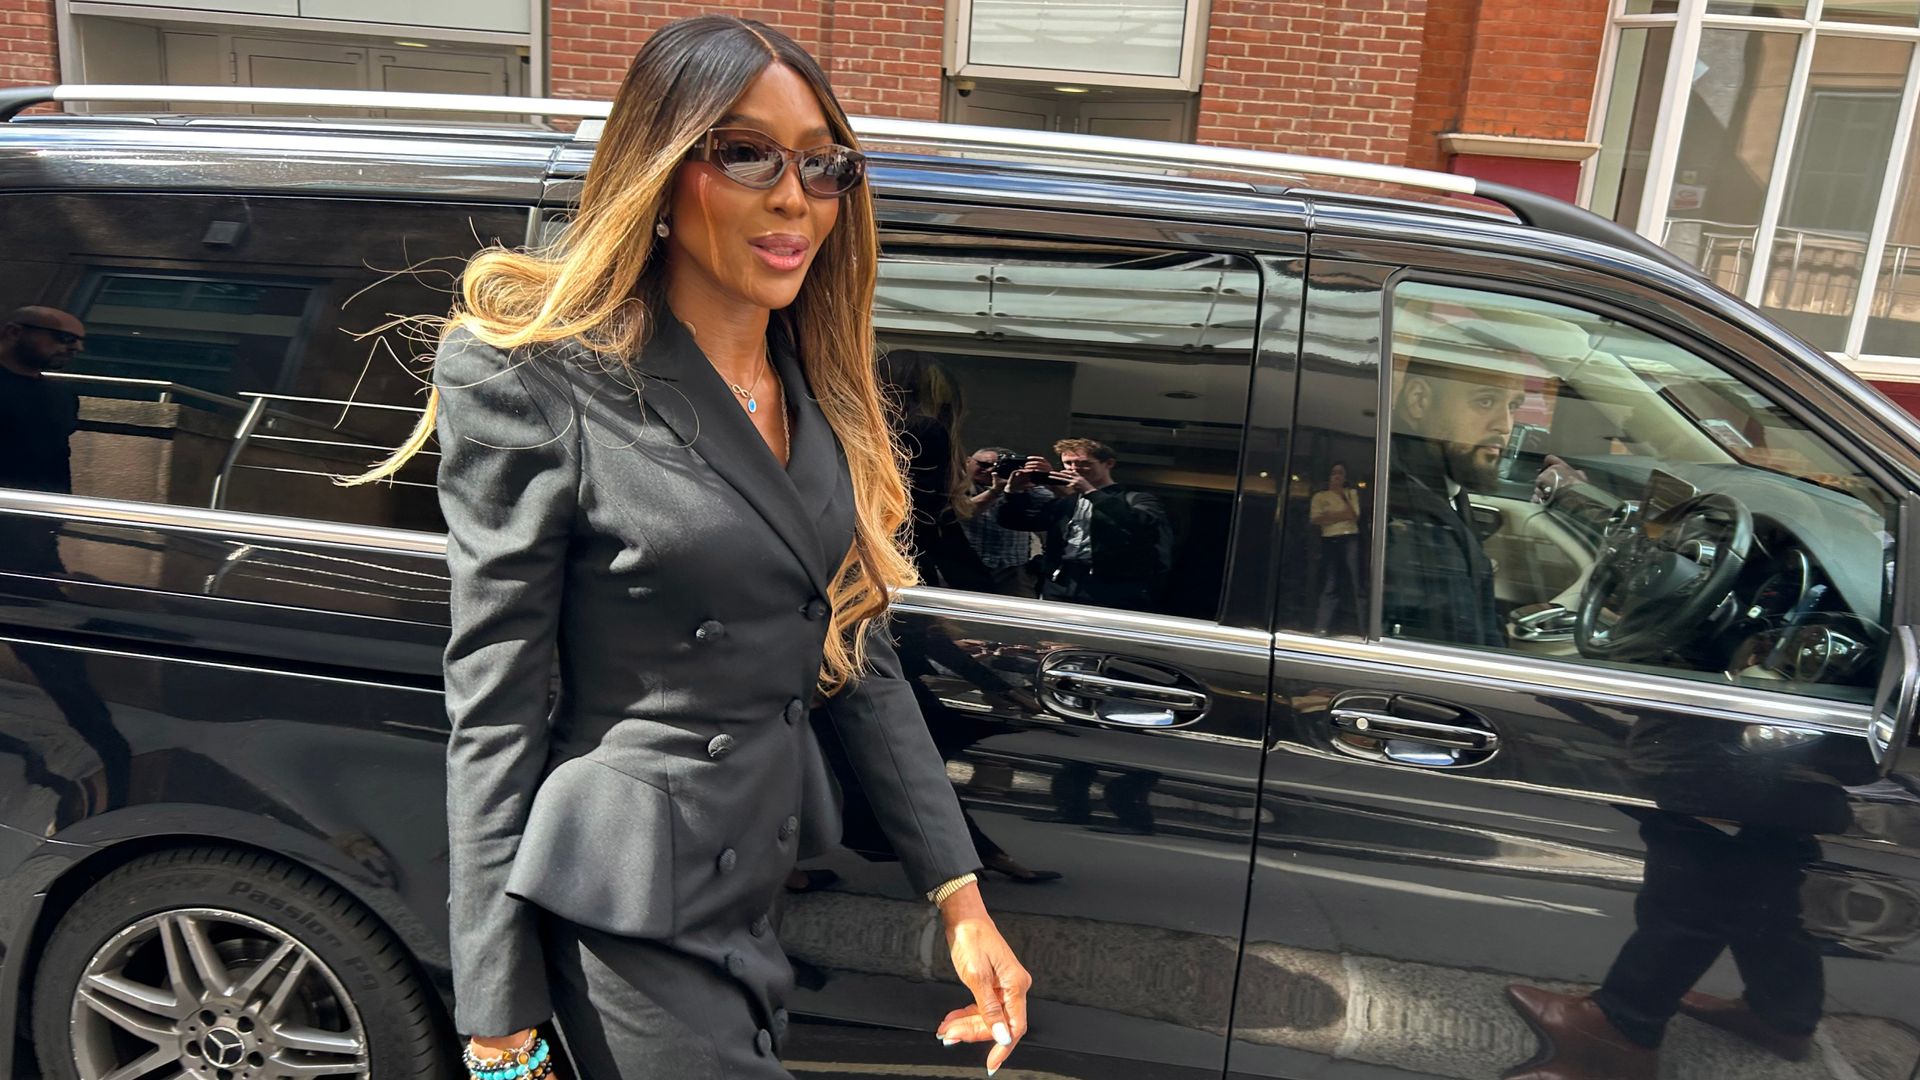
Regulatory frameworks governing non-profit organizations assume a rational distribution of labor where trustees maintain active oversight over financial flows. When high-profile entities lend their brand equity to charitable vehicles, structural vulnerabilities emerge. The legal dispute surrounding Naomi Campbell, the dissolution of Fashion for Relief, and the subsequent tribunal ruling to overturn a trustee disqualification ban expose the systemic risks inherent in celebrity-backed philanthropy. Deconstructing this case reveals the operational mechanics of trustee delegation failure, the mechanics of internal deception, and the precise boundaries of legal liability under English charity law.
The Principal-Agent Disconnect in Non-Profit Governance
In standard corporate governance, the principal delegates authority to an agent while maintaining structural checkpoints. In high-profile philanthropic vehicles, this dynamic often distorts. The celebrity founder functions primarily as a marquee asset intended to maximize donor acquisition and public relations value, while operational management, financial administration, and compliance are delegated to specialized personnel or co-trustees.
This division of labor creates an asymmetrical information environment. The celebrity principal relies on administrative proxies to handle ledger entries, regulatory filings, and expense categorizations. When those proxies operate without rigorous internal controls, the structural integrity of the organization collapses.
The mechanism of failure typically follows a three-stage sequence:
- Brand Capitalization: The organization leverages the celebrity's global profile to attract high-net-worth donors and secure high-visibility events, generating substantial inflows.
- Delegation Abdication: Administrative and financial oversight is ceded entirely to operational managers or co-trustees under the assumption of baseline competency and ethical compliance.
- Control Blind Spots: Without routine internal audits or dual-authorization controls, bad actors can obscure expenditures, mischaracterize personal expenses as operational overhead, and falsify records.
The Cost Function of Delegated Oversight
Regulatory bodies such as the Charity Commission operate on strict statutory principles: legal responsibility rests with every appointed trustee, regardless of whether they exercise active management or passively endorse operations. This creates a severe compliance penalty for celebrity founders who treat trusteeship as an honorary title rather than an active fiduciary obligation.
The legal jeopardy centers on the failure of supervision. Under regulatory statutes, a trustee who allows others to run the charity without adequate oversight breaches their core duty. However, the tribunal's intervention in the Campbell case establishes a crucial legal distinction: passive delegation differs fundamentally from active complicity or knowing participation in financial misconduct.
When funds earmarked for charitable initiatives are diverted to cover luxury accommodations, spa treatments, or personal expenses, the immediate symptom is financial leakage. The deeper structural failure, however, is the absence of verification protocols. Without mandatory dual-signature approvals for expenditures exceeding defined thresholds, discretionary spending remains unchecked.
The Mechanics of Internal Deception
In complex governance failures, regulatory investigations often uncover intentional obfuscation by administrative insiders. The legal defense mounted in the tribunal highlighted a pattern of systematic deception wherein a co-trustee concealed financial allocations and operational missteps from the primary founder.
This dynamic relies on informational gatekeeping. If a single individual controls both the narrative presented to the board and the direct communication with external accountants or regulators, they establish a single point of failure. The primary trustee receives sanitized summaries, oral assurances, or forged documentation, masking the underlying drainage of capital.
The exposure of such schemes typically occurs via external regulatory audits or whistleblowing protocols rather than internal discovery, indicating that standard governance checks within celebrity-led charities often lack the internal friction required to intercept fraud early.
Re-Engineering Charitable Architecture
To prevent regulatory disqualifications and systemic fund misappropriation, high-profile philanthropic vehicles must transition from personality-driven models to institutionalized operating structures.
The remediation framework requires three structural mandates:
- Mandatory Independent Auditing: External financial reviews must occur on a quarterly basis, bypassing administrative gatekeepers and reporting directly to all active trustees simultaneously.
- Segregation of Duties: The individual holding brand equity or executive public roles must be structurally barred from controlling disbursement authorizations without independent co-signers from institutional accounting firms.
- Active Fiduciary Training: Regulatory compliance must be treated as a rigorous operational requirement, ensuring that every trustee understands that statutory liability cannot be outsourced to administrative staff.
The legal victory in overturning a trustee ban does not erase the underlying governance deficit. It merely clarifies that the law recognizes the boundary between systemic deception by an agent and willful misconduct by a principal. For the broader philanthropic sector, the lesson is stark: brand prestige is not a substitute for internal controls, and passive oversight is an invitation to regulatory collapse.


